>_
Latest
Why Japan’s markets flipped the usual script after central bank rate hike // Women Leaders Association Names Denise Byers as Minneapolis Coaching Partner, Expanding the Chapter's Vetted Coaching Roster // Women Leaders Association Names Kate Zappitelli as First Denver Coaching Partner, Bringing an Executive Team Alignment Expert to Colorado's Women Professionals // Women Leaders Association Names Shelley A. Smith as First Milwaukee Coaching Partner, Bringing a Coach Who Trains and Credentials Other Coaches // Australia news live: RBA governor paves way for rate hike; Labor to ‘look at’ following Canada in pulling closer to EU // Why do ‘never smokers’ get lung cancer? In some cases, rare genetic variant may be a factor // Women Leaders Association Names Kerry Hoffman as First Indianapolis Coaching Partner, Bringing a Research-Backed Method for Women Who Keep Saying "Later" // Women Leaders Association Adds Mimi Throckmorton as San Diego Coaching Partner, Bringing a Small Business Coach for Owners // Why Japan’s markets flipped the usual script after central bank rate hike // Women Leaders Association Names Denise Byers as Minneapolis Coaching Partner, Expanding the Chapter's Vetted Coaching Roster // Women Leaders Association Names Kate Zappitelli as First Denver Coaching Partner, Bringing an Executive Team Alignment Expert to Colorado's Women Professionals // Women Leaders Association Names Shelley A. Smith as First Milwaukee Coaching Partner, Bringing a Coach Who Trains and Credentials Other Coaches // Australia news live: RBA governor paves way for rate hike; Labor to ‘look at’ following Canada in pulling closer to EU // Why do ‘never smokers’ get lung cancer? In some cases, rare genetic variant may be a factor // Women Leaders Association Names Kerry Hoffman as First Indianapolis Coaching Partner, Bringing a Research-Backed Method for Women Who Keep Saying "Later" // Women Leaders Association Adds Mimi Throckmorton as San Diego Coaching Partner, Bringing a Small Business Coach for Owners //
Business

UK government borrowing costs soar to a 28-year high ahead of Budget

Long-term borrowing costs for the UK government have surged to their highest levels in 28 years , placing additional pressure on Andy Burnham’s team ahead of next month’s Budget.

UK government borrowing costs soar to a 28-year high ahead of Budget

Long-term borrowing costs for the UK government have surged to their highest levels in 28 years , placing additional pressure on Andy Burnham’s team ahead of next month’s Budget. The surge coincided with a broad global sell-off in debt markets, fuelled by fears of escalating oil prices and wider uncertainty surrounding future inflation. Yields on 30-year UK government bonds – also referred to as gilts – increased by 10 basis points to hit 5.89 per cent on Tuesday morning, their highest level since March 1998.

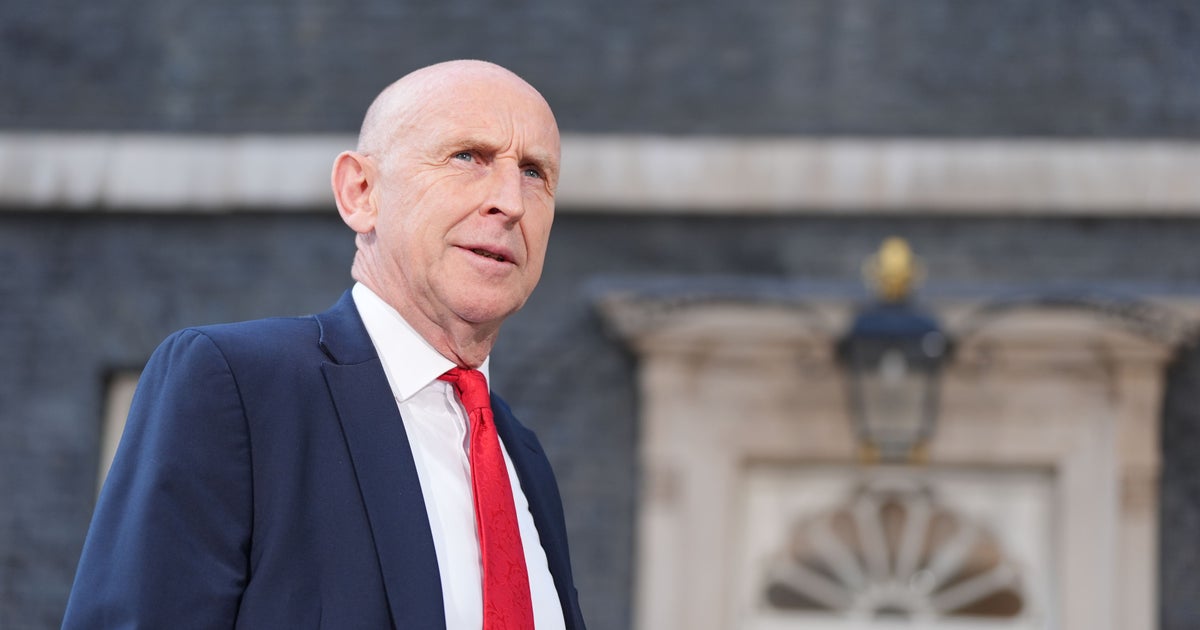
The yield on benchmark 10-year gilts also rose sharply, reaching up to 5.223 per cent – the most elevated rate observed since June 2008, during the peak of the financial crisis. These higher bond returns ultimately mean that borrowing money will prove more expensive for Mr Burnham and vhancellor John Healey. Bond yields move in the opposite direction to their market value, meaning prices drop as yields climb.

The yield on 30-year UK government bonds – also known as gilts – jumped by 10 basis points to 5.89 per cent on Tuesday morning, hitting the highest level since March 1998. (PA Wire) Japan’s 10-year bond yield also swung to its highest since 1996 on Tuesday after rising above 3 per cent. The global uptick in yields is partly linked to signs of escalation in the Middle East, alongside concerns that inflation could accelerate in the coming months and lead central banks to lift their interest rates. Oliver Faizallah, head of fixed income research at Raymond James, said: “While elevated bond yields are warranted given the inflationary and fiscal risks that are very clear and present, I also believe that the recent sell-off is fully pricing in these risks.

“As it stands, bond yields are priced for higher and prolonged second round inflation, consequent central bank hikes, and further government spending driven by an increase in bond sales. “With the bad news in the price, there is a limitation to how much further bond yields can keep climbing.”

Source: The Independent
Distributed to Wire · Sterling Post by RedPress.

Related News

Contact Advertise Search RSS